Salary sacrifice
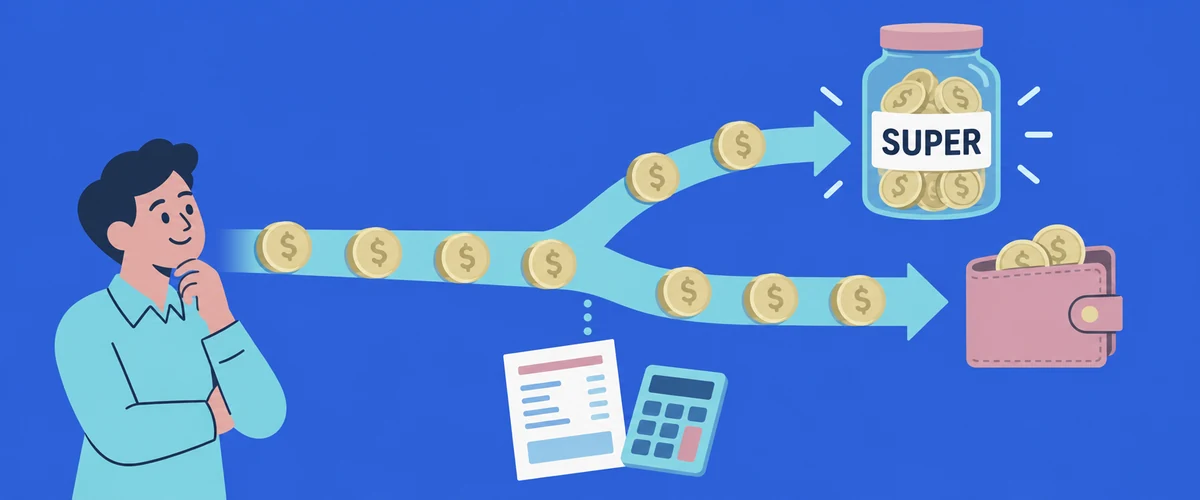
Salary sacrifice is an agreement with your employer to give up part of your future pre-tax pay in exchange for benefits of similar value, such as extra super, a car through a novated lease, or everyday expenses if you work for a charity or public hospital. Because the sacrificed amount comes out before income tax, your taxable income falls and you may pay less tax overall.
Whether it's worth doing depends on your tax rate, what you're sacrificing for, and whether you can manage on a smaller pay packet. This guide explains how the arrangements work, walks through a worked example using 2026-27 rates, and covers the situations where the saving is smaller than it first looks. It's general information rather than personal financial advice, so for a decision about your own money, a licensed financial adviser or registered tax agent can look at the whole picture.
How a salary sacrifice arrangement works
You and your employer agree that you'll receive less salary, and the employer uses that money to pay for a benefit on your behalf. The ATO also calls this salary packaging or total remuneration packaging, and its guide to salary sacrificing for employees sets out what makes an arrangement effective for tax purposes. You need to:
- agree to the arrangement before you do the work the pay relates to
- have an agreement with your employer, which is usually in writing
- have no access to the sacrificed salary while the arrangement runs
The first condition means you can only sacrifice future pay. Salary, leave, bonuses or commissions you've already earned can't be packaged, and if an arrangement doesn't meet the conditions, the benefits are taxed as ordinary income. Expenses paid by direct debit from your pay aren't salary sacrifice either, even though the money leaves before it reaches your account.
Employers don't have to offer every kind of benefit. Most will let you sacrifice into super, but what else you can package depends on the employer and, often, on the salary packaging provider they use. Subject to your employment contract or agreement, you can renegotiate an arrangement at any time.
Salary sacrificing into super
Super is the arrangement most people can access. Sacrificed super counts as a concessional (before-tax) contribution, and your fund taxes it at 15% instead of your marginal tax rate. For anyone earning more than $45,000, the marginal rate plus the 2% Medicare levy is at least 32%, so each dollar sacrificed can put more into your super than the same dollar would have added to your take-home pay.
Sacrificing doesn't reduce your employer's own contribution. The super guarantee rate for 2026-27 is 12%, and the ATO states that your employer must still pay your full super guarantee as though there were no salary sacrifice. Your sacrificed amount sits on top of it.
There is a yearly limit. The concessional contributions cap for 2026-27 is $32,500, up from $30,000 the year before, and it covers everything before tax: your employer's super guarantee, your salary sacrifice and any personal contributions you claim as a deduction, across all your funds. Contributions over the cap are added to your taxable income and taxed at your marginal rate, so it's worth adding up what your employer already pays before you choose an amount.
If your total super balance was under $500,000 on 30 June of the previous financial year, you may be able to use unused cap amounts from up to five earlier years. This can help if you've had time out of the workforce or years when you couldn't afford to contribute.
A worked example for 2026-27
Take someone on a salary of $90,000 who asks their employer to sacrifice $5,000 a year into super. The table uses the 2026-27 resident tax rates and the 2% Medicare levy, and assumes no other income, deductions, offsets, HELP debt or Medicare levy surcharge.
| No salary sacrifice | $5,000 salary sacrifice | |
|---|---|---|
| Taxable income | $90,000 | $85,000 |
| Income tax | $17,520 | $16,020 |
| Medicare levy | $1,800 | $1,700 |
| Take-home pay | $70,680 | $67,280 |
| Employer super guarantee (12% of $90,000) | $10,800 | $10,800 |
| Sacrificed contribution after 15% contributions tax | nil | $4,250 |
Take-home pay falls by $3,400, while $4,250 is added to super after the fund's contributions tax. The $850 difference is the tax saving, and it comes from each sacrificed dollar being taxed at 15% instead of 32%. The person's total concessional contributions would be $15,800, well under the $32,500 cap.
The trade-off is access. Money in super is generally preserved until you reach your preservation age and retire, or meet another condition of release, so a saving on paper doesn't help if you need that $3,400 for rent or bills this year. Moneysmart's super contributions optimiser lets you compare before-tax and after-tax contributions using your own figures.
When the saving is smaller
The example sits in the 30% tax bracket. At either end of the income range, the numbers work out differently.
On a lower income. Taxable income between $18,201 and $45,000 is taxed at 15% in 2026-27, the same rate your fund charges on concessional contributions, so there's little tax to save and your money becomes harder to reach. If your income is $37,000 or less, the government's low income super tax offset generally returns the 15% contributions tax to your fund, up to $500 a year. That refund already applies to your employer's contributions, with or without salary sacrifice.
On a high income. If your income plus concessional contributions is more than $250,000, Division 293 tax adds another 15% on the contributions above that threshold, so they're effectively taxed at 30%. The cap also leaves less room. At a salary of around $270,000, the 12% super guarantee on its own reaches the $32,500 cap, and employers can stop paying super guarantee once your earnings for the year pass the 2026-27 maximum contribution base of $270,830.
When income tests apply. A lower taxable income doesn't always mean a lower income for other purposes. The ATO notes that a salary sacrifice arrangement may affect the Medicare levy surcharge, compulsory study and training loan repayments such as HELP, some tax offsets, child support and some government benefits. Many packaged benefits appear on your income statement as reportable fringe benefits, and those amounts can be counted when these tests are worked out.
Packaging benefits other than super
Outside super, most packaged benefits are fringe benefits, and your employer pays fringe benefits tax (FBT) on them at 47%. To reduce the FBT, your employer may ask you to pay part of the benefit's value from your after-tax pay, which is called an employee contribution. Packaging providers may also charge set-up or administration fees, which reduce your saving.
Some work-related items are exempt from FBT when your employer provides them, including a portable electronic device, computer software, protective clothing, a briefcase and tools of trade. The ATO has advised that from 1 April 2027 these items will no longer be exempt when they're provided through a salary sacrifice arrangement, so check when any item you're considering would be provided.
Novated leases and electric cars
A novated lease is a three-way agreement between you, your employer and a finance company, where your employer makes the lease payments from your pre-tax salary and usually pays the running costs as well. Using the statutory formula, the car's taxable value is 20% of its cost each year, whatever distance you drive, and employee contributions from your after-tax pay can be used to reduce it.
Eligible electric cars are treated differently. Under the electric cars exemption, no FBT is payable on the private use of a car, or on its registration, insurance, maintenance and charging costs, when:
- it's a battery electric or hydrogen fuel cell car
- it was first both held and used on or after 1 July 2022
- luxury car tax has never been payable on its importation or sale
Plug-in hybrids have not been eligible for new arrangements since 1 April 2025, apart from some that already qualified. Even when the exemption applies, the benefit is still reportable, so it can count in the income tests described above.
A car lease is a larger commitment than a super contribution. Before signing, it may help to compare the total cost over the lease, including interest, fees and the residual payment at the end, with buying the same car another way. Ask the provider what happens to the lease and its payments if you change jobs or stop working.
Working for a charity, public hospital or ambulance service
Employees of public benevolent institutions, health promotion charities, public and not-for-profit hospitals and public ambulance services may be able to package everyday expenses such as rent, mortgage repayments or bills, because their employers are exempt from FBT up to a cap for each employee.
| Employer type | Grossed-up cap per FBT year | Approximate amount you can package for expenses without GST |
|---|---|---|
| Public benevolent institution or health promotion charity | $30,000 | $15,900 |
| Public or not-for-profit hospital, public ambulance service | $17,000 | $9,010 |
The caps apply to the "grossed-up" value of the benefits, a figure higher than the amount you actually receive, so the amount you can package is roughly half the headline cap. The figures in the last column divide the cap by the ATO's lower gross-up rate of 1.8868, which applies when the employer can't claim GST credits, such as for mortgage repayments or rent.
A separate $5,000 grossed-up cap applies to salary packaged meal entertainment and entertainment facility leasing. The FBT year runs from 1 April to 31 March, and these caps apply to the years ending 31 March 2023 to 31 March 2027. Packaged benefits from these employers are still reportable, even though no FBT is paid on them.
Questions to ask before you agree
Your employer or its packaging provider should be able to answer these before you sign anything:
- What fees apply, and are they taken from your pre-tax or after-tax pay?
- Will your overtime, leave loading or any other entitlements still be worked out on your pre-sacrifice salary?
- How will the sacrificed amounts appear on your payslip and income statement?
- How do you change the amount or end the arrangement, and how much notice is needed?
- What happens to the arrangement if you leave the job?
If you're weighing up a job offer or a pay review that's described as a total package, ask for the breakdown between base salary, super and any packaged benefits so you can compare it fairly. Our guide to asking for a pay rise covers how to prepare for that conversation, and the average salary in Australia explains what the published pay figures include.
Article sources
- Australian Taxation Office, guide to salary sacrificing for employees
- Moneysmart, super contributions optimiser
- Australian Taxation Office, low income super tax offset
- Australian Taxation Office, Division 293 tax
- Australian Taxation Office, electric cars exemption
- Australian Taxation Office, exempt from FBT up to a cap
- Australian Taxation Office, contributions caps
- Australian Taxation Office, super guarantee
- Australian Taxation Office, tax rates australian residents
- Moneysmart, salary packaging
- Moneysmart, super contributions
- Australian Taxation Office, division 293 tax
- Australian Taxation Office, fringe benefits tax rates and thresholds
- Australian Taxation Office, fbt changes for salary sacrificed work related benefits
- Australian Taxation Office, car leasing and fbt
Related articles
How to ask for a pay rise, and back it up with real numbers
What national wage growth looks like right now, how to work out a figure for your own role, wording you can adapt for the conversation, and what to do if the answer is no.
The average salary in Australia (2026)
Full-time adults in Australia averaged $2,083.70 a week in May 2026. Several measures get called the average salary, and this explains which one fits your situation.
Behavioural interview questions and how to answer them
How to answer behavioural interview questions using STAR, with common questions, what they test, an example answer and tips for follow-up questions.